

6 August 2026, 12:44
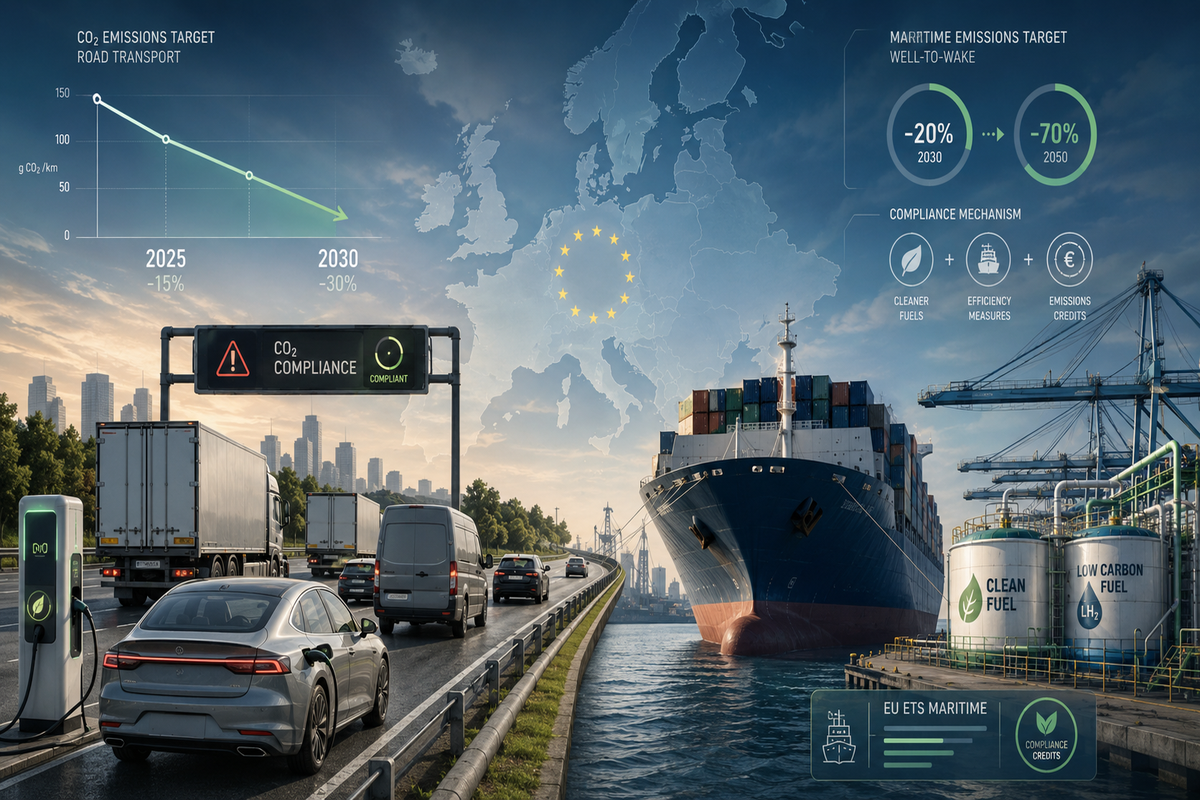
European transport networks stand at a pivotal juncture as statutory climate targets for 2025 and 2030 force simultaneous adjustments across road and maritime supply chains. With domestic transport generating a quarter of all greenhouse gas emissions across the European Union, regulatory frameworks are tightening rapidly to drive the region toward its European Green Deal target of a 90% reduction in transport emissions by 2050. However, recent data highlights significant operational hurdles on both land and sea. On land, a temporary slowdown in battery electric vehicle adoption has stalled improvements in average fleet emissions, leaving automotive manufacturers scrambling to meet aggressive step-downs in allowable fleet carbon intensity arriving in 2025. At sea, European nations are lobbying the International Maritime Organization for early-stage financial incentives to bridge the steep cost gap between fossil and zero-emission fuels, even as localized biofuel shortages at major hubs like the Port of Rotterdam send compliance credit prices surging. As regulatory deadlines near, both terrestrial automakers and maritime bunkering suppliers face immense financial and operational pressure to align immediate market realities with long-term net-zero goals.
Fleet compliance and the plateau in electric vehicle adoption
Advertisement
European road transport faces a critical transition phase as statutory regulatory standards tighten while zero-emission vehicle adoption shows signs of stagnation. Because domestic transport accounts for one quarter of all greenhouse gas emissions in the European Union, meeting the stringent fleet-wide limits arriving in 2025 requires immediate operational adjustments from automotive manufacturers.
Transitioning to stricter 2025 fleet emission limits
The European Union has established progressively tighter fleet-wide carbon dioxide emission targets under Regulation (EU) 2019/631 to align the road sector with the broader European Green Deal goal of a 90% reduction in transport emissions by 2050. For the 2020-2024 compliance period, the passenger car target stood at 95 gCO2/km NEDC, which corresponds to approximately 115.1 gCO2/km under the Worldwide Harmonised Light Vehicles Test Procedure (WLTP). For light commercial vehicles (vans), the equivalent 2020-2024 benchmark was set at 130 gCO2/km NEDC, or 189.9 gCO2/km WLTP. [1]
Starting in 2025, manufacturers face a sharp step-down in allowable carbon intensity across their sold fleets, creating significant compliance pressure. The regulation mandates the following multi-year trajectory for fleet-wide average emissions:
-
Passenger cars (WLTP target threshold):
-
2025-2029: 93.6 gCO2/km
-
2030-2034: 49.5 gCO2/km
-
2035 onward: 0.0 gCO2/km
-
-
Vans / Light commercial vehicles (WLTP target threshold):
-
2025-2029: 153.9 gCO2/km
-
2030-2034: 90.6 gCO2/km
-
2035 onward: 0.0 gCO2/km
-
Electric vehicle slowdown halts road transport progress
Progress in lowering average vehicle emissions in Europe stalled in 2024 following several years of consistent reductions. Between 2019 and 2023, average CO2 emissions from new passenger cars fell by 28%, while emissions from new vans declined by 11.4%. However, 2024 data from the European Environment Agency highlights a complete halt in passenger car decarbonisation progress and a slight reversal in the light commercial vehicle segment. [2]
Stagnation in battery electric passenger car registrations
Average emissions from newly registered passenger cars remained flat in 2024 at 106.7 gCO2/km WLTP. The lack of further reductions stems primarily from a drop in the market share of battery electric vehicles (BEVs), which contracted from 15.5% of new car registrations in 2023 to 14.5% in 2024. Petrol vehicles, including conventional hybrids, continued to dominate the market by representing over half of all new registrations, while diesel models accounted for 15.1%.[3]
Market dominance of diesel vans and light commercial vehicle trends
The light commercial vehicle market experienced an outright increase in carbon intensity during 2024, with average CO2 emissions rising by 2.3% year-on-year to 184.9 gCO2/km WLTP. This reversal was driven by a two percentage point decline in battery electric van adoption, which dropped from an 8.2% market share in 2023 down to 6.2% in 2024. Conventional diesel vans retained overwhelming market dominance, comprising 87% of all new light commercial vehicle registrations across the region.[4]
Pool performance across passenger car and van manufacturers
To fulfill regulatory obligations, vehicle manufacturers can form compliance pools to combine their annual fleet registrations and meet binding specific emission targets calculated according to fleet mass. In 2024, virtually all major car and van pools successfully met their binding annual targets, covering 94% of total vehicle registrations across the EU, Iceland, and Norway.[5]
Maritime decarbonisation hits policy bottlenecks and fuel supply deficits
While terrestrial transport works to overcome fleet-wide vehicle hurdles, the European maritime sector is confronting regulatory uncertainty on international policy and localized fuel deficits in key regional bunkering hubs. Achieving maritime net-zero goals requires aligning international policy frameworks with physical supply chain capabilities across major ports.
European push for early incentives in the IMO net-zero framework
To establish global alignment for maritime decarbonisation, the European Commission and 27 European nations - including major maritime states such as Greece, Denmark, Germany, Cyprus, Malta, and the Netherlands - submitted a comprehensive joint proposal to the International Maritime Organization (IMO) ahead of the 22nd session of the Intersessional Working Group on GHG Emissions from Ships (ISWG-GHG 22). The co-sponsoring nations are urging the IMO to integrate direct economic incentives into its upcoming Net-Zero Framework (NZF) to accelerate the early adoption and production of zero and near-zero greenhouse gas (ZNZ) marine fuels. Transitioning global commercial shipping toward zero-emission energy sources requires immense, long-term capital investments in vessel design, fuel production facilities, and port bunkering infrastructure.[6]
Balancing cost differentials for zero and near-zero emission fuels
Because shipping operators function within highly competitive global markets, the co-sponsors emphasized that adopting clean alternative fuels must become economically attractive compared to continuing the use of conventional high-GHG fuels. During the initial phases of the energy transition, ZNZ fuels carry significant cost premiums compared to traditional marine fuels. European policymakers argue that early-stage incentive mechanisms must be implemented to bridge this price gap directly, absorbing the additional expenditure incurred by pioneering vessel operators and fuel suppliers.[7]
Demand certainty and flexibility mechanisms for global shipping fleets
Providing predictable, long-term demand certainty is critical to de-risking private sector investments across the maritime value chain and preventing the creation of stranded assets. Beyond financial support, European co-sponsors acknowledge that technical constraints or localized fuel shortages will prevent some vessel operators from meeting strict greenhouse gas intensity targets immediately. To preserve a fair competitive environment without penalizing early movers, the European proposal advocates for combining clear transition pathways toward net-zero by or around 2050 with flexible, enforceable compliance mechanisms.[8]
The core priorities established in the European submission to the IMO include:
-
Economic bridge incentives: Financial mechanisms to offset the higher cost of ZNZ fuels during initial rollout phases.
-
Regulatory demand predictability: Clear multi-decade timelines to de-risk port infrastructure and vessel investments.
-
Flexible compliance pathways: Mechanisms to accommodate vessels facing localized fuel availability constraints without diluting overall climate targets.
-
Equitable transition support: Protections designed to support least developed countries and small island developing states.
Biofuel shortfalls drive up compliance credit costs in the Netherlands
While global policy negotiations progress at the IMO level, regional supply constraints are creating acute compliance pressures within European ports. In the Netherlands, national regulations mandate that marine fuel suppliers achieve a 2.9% reduction in greenhouse gas emissions in 2026, scaling up to an 8.2% reduction by 2030 against a baseline of 94g CO2e/MJ. Suppliers demonstrate compliance by surrendering tradeable renewable fuel units known as ZRE-G tickets, which are generated when renewable fuels are physically blended and supplied to maritime vessels.[9]
Supply deficits at the Port of Rotterdam and fine risks for suppliers
Sales data from the Port of Rotterdam - Europe's largest bunkering hub - indicates that despite year-on-year increases in marine biodiesel sales, physical blending volumes remain below the thresholds required to generate sufficient ZRE-G tickets for all Dutch fuel suppliers to satisfy their 2026 mandates. This supply deficit threatens fuel suppliers who planned to meet compliance obligations by purchasing excess tickets from compliant peers rather than physically blending biofuels. Because non-compliance carries severe administrative fines of up to 10% of a company's annual turnover from the preceding year, buyers rushed to secure available compliance credits, driving ZRE-G prices to a four-month high of 13.40c/kgCO2e (equivalent to $456 per tonne of Advanced Fame blended). Furthermore, cross-sector credit transfers offer minimal relief, as road transport compliance tickets (LRE-Gs) trade at four to five times the price of marine tickets.[10]
Shifting economics between physical bio-bunkering and ticket trading
The escalation in ZRE-G compliance ticket costs has significantly altered market dynamics for physical marine biofuels in the Netherlands. In late July 2026, outright prices for B100 Advanced fatty acid methyl ester (Fame) dropped below Marine Gasoil (MGO) prices for the first time since dedicated tracking began, falling to $1,286.50 per tonne compared to MGO at $1,288.50 per tonne. While physical bio-bunkering offers substantial net savings for vessel owners when accounting for regulatory benefits under the EU Emissions Trading System (EU ETS) and FuelEU Maritime, those net financial advantages have narrowed as secondary market values for FuelEU surplus credits declined from €215 per tonne in early 2026 to €120 per tonne in July 2026.[11]
Source Links:
1. https://www.eea.europa.eu/en/analysis/indicators/co2-performance-of-new-passenger
https://www.eea.europa.eu/en/analysis/indicators/co2-performance-emissions-of-new
2. https://www.eea.europa.eu/en/analysis/indicators/co2-performance-of-new-passenger
https://www.eea.europa.eu/en/analysis/indicators/co2-performance-emissions-of-new
3. https://www.eea.europa.eu/en/analysis/indicators/co2-performance-of-new-passenger
4. https://www.eea.europa.eu/en/analysis/indicators/co2-performance-emissions-of-new
5. https://www.eea.europa.eu/en/analysis/indicators/co2-performance-of-new-passenger
https://www.eea.europa.eu/en/analysis/indicators/co2-performance-emissions-of-new
Source: LECTURA GmbH
Set LECTURA Press as your preferred source


